…Highlights gains in GDP growth, investment inflows, manufacturing and economic diversification
MON OCT 26 2026-theGBJournal| President Bola Ahmed Tinubu has said that his administration is rewriting Nigeria’s decades-long story of economic underperformance through far-reaching reforms designed to dismantle structural barriers, unlock the nation’s enormous potential and deliver jobs, productivity and shared prosperity.
According to him, the administration is currently undertaking what it came into office to achieve: rewriting the story of a nation that has performed below its potential for far too long.
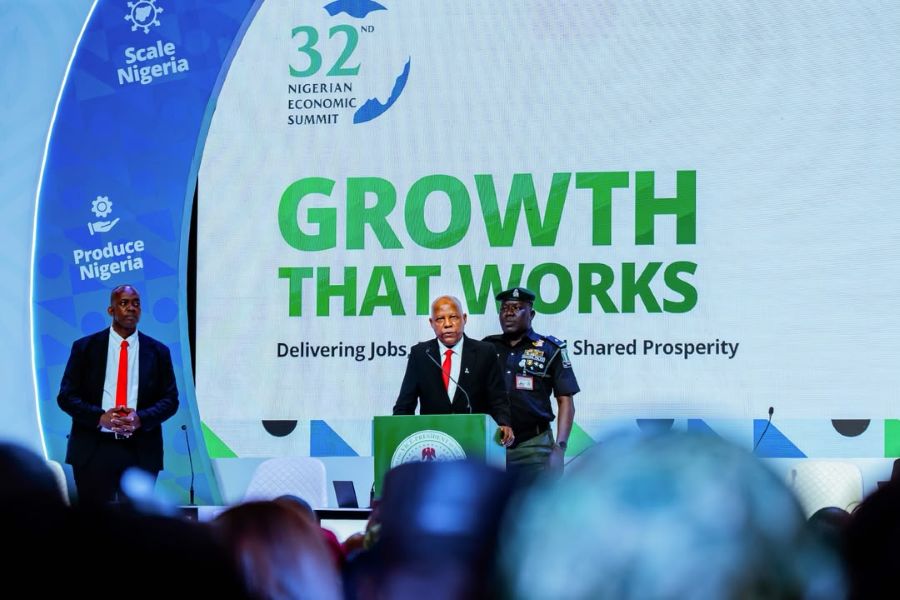
Speaking on Monday in Abuja when he formally declared open the 32nd Nigerian Economic Summit, the Nigerian leader, who was represented by his deputy, Vice President Kashim Shettima, noted that his administration began on a difficult note because there is no shortcut to economic growth.
“Distinguished ladies and gentlemen, we came to rewrite the story of a nation that has performed below its potential for far too long. But there is no shortcut to economic growth. This is why we began with a difficult reset. For us, rescuing the economy means rescuing livelihoods and transforming the fortunes of young jobseekers, farmers, manufacturers, entrepreneurs and innovators.
“We cannot harness the immense opportunities offered by our growing population without first stabilising the economy. We must also create the conditions for the public and private sectors to invest, expand and generate productive employment,” he explained.
President Tinubu observed that the summit’s theme, “Growth That Works: Delivering Jobs, Productivity and Shared Prosperity,” built on the ambition of the previous edition of the annual event to achieve a prosperous and inclusive Nigeria by 2030.
He noted that his administration has “since set in motion a series of reforms to dismantle the structural barriers that have prevented our abundant human and natural resources from yielding prosperity.”
“These reforms are restoring confidence, strengthening our economic foundations and laying the groundwork for sustainable growth,” he added, noting that the administration is encouraged by what it has accomplished so far.
Acknowledging that creating jobs was only half the task, the Nigerian leader stressed the need to “improve the quality of work, reduce underemployment and harness the potential” of the nation’s underutilised workforce.
He continued: “Our pursuit of prosperity demands greater productivity from every worker, enterprise and investment. We must judge infrastructure by the economic activity it generates and education by the skills and productivity it delivers.
“We must judge industrial policy by the competitiveness of our firms and investment incentives by the capital, technology, exports and jobs they attract.”
The President outlined what he described as the achievements of his administration’s reforms, saying they have been well documented. He cited figures from the National Bureau of Statistics indicating that Nigeria’s inflation-adjusted GDP grew by 3.89% in the first quarter of 2026, compared with 3.13% a year earlier.
On economic diversification, he stated that “non-oil activities accounted for 96.08% of GDP, while manufacturing grew by 3.29% and the oil sector by 2.57%,” emphasising that the gains have reinforced his administration’s confidence in the path of recovery and diversification.
President Tinubu stated, however, that his administration’s ambition must go beyond favourable statistics, even as the development narrative is changing and investor confidence is returning.
Outlining the administration’s gains so far, he said, “In the first quarter of 2026, our capital importation reached $10.37 billion, an increase of 83.83% over the corresponding period in 2025. This comprised both portfolio and foreign direct investment. We will, therefore, continue to ease regulatory burdens, strengthen transparency and policy predictability, and expand access to finance.
“Our tax reforms seek to build a modern, equitable system that finances development and gives businesses certainty. This discipline must guide our investments in all sectors of the economy, including energy, agriculture and solid minerals. We are reforming the electricity market to improve supply and attract investment in generation, transmission, distribution and alternative energy.”
On agriculture, the President said the administration is connecting farms to storage facilities, processing centres and markets while expanding irrigation, mechanisation, finance and rural infrastructure. He added that the government is also seeking “to move beyond extraction into domestic processing, industrial production and exports” in the solid minerals sector.
He, however, noted that despite the gains of his administration’s economic reforms, the task remains far from finished, even as young Nigerians have demonstrated their capacity to compete globally in technology, financial services and the creative industries.
For her part, the United Nations Deputy Secretary-General, Dr. Amina Mohammed, assessed the reforms implemented under the Tinubu administration, acknowledging the gains while urging their urgent consolidation and stabilisation, as well as the effective management of expectations among citizens and other stakeholders.
She also applauded the African Development Bank (AfDB) for its new financial architecture for development across the African continent, particularly its prioritisation of financing programmes that target impactful development.
In his remarks, the Minister of Finance and Coordinating Minister of the Economy, Dr. Taiwo Oyedele, presented the Nigerian Economic Policy Framework, which he described as a national economic doctrine that establishes how Nigeria makes economic decisions and measures real progress.
The minister invited members of the Nigerian Economic Summit Group (NESG) and private sector experts to make valuable contributions to the development of the framework by rigorously critiquing the draft proposal with facts and figures.
He said the principles underpinning the framework include enterprise, open but fair markets, and whole-of-government coherence.
The minister also listed key areas of focus in the proposed framework, including economic stability, human capital development and productivity, among others.
In his welcome address, the Chairman of the NESG, Mr. Olaniyi Yusuf, said participation at the 32nd summit reflected stakeholders’ commitment to contributing to inclusive and impactful growth, while acknowledging the Federal Government’s efforts to improve the ease of doing business in the country.
He said that although the reforms of the Tinubu administration may have introduced significant changes to Nigeria’s economic structures, the task before economic experts at the summit and beyond was to ensure stabilisation rather than seek a reversal of the policies.
Yusuf added that the 32nd edition of the summit must help Nigeria move from policy consensus to a framework that resolves practical issues, noting that deliberations would be guided by proposals for job creation, improved productivity and shared prosperity for all.
Also speaking, the Chairman and Founder of BUA Group, Abdul Samad Rabiu, commended the economic reforms of President Bola Ahmed Tinubu’s administration, saying they had begun to address longstanding challenges confronting Nigerian businesses.
Rabiu acknowledged the difficulties experienced by ordinary Nigerians but noted that improvements in access to foreign exchange had created a more predictable environment for businesses.
“For many years, one of the greatest challenges facing businesses was access to foreign exchange. You could have all the naira but be unable to obtain the foreign exchange needed to buy raw materials and machinery,” he recalled.
X-@theGBJournal|email:gbj@govbusinessjournal.com|govandbusinessj@gmail.com